Conversion Economics and Financial Modeling
Acquiring distressed office assets drastically lowers upfront capital expenditure. The average acquisition price for Class B/C CBD office properties in the U.S. has fallen from $250–$300 to $110–$140 per square foot. Ground-up construction costs for comparable assets exceed $350 per square foot.
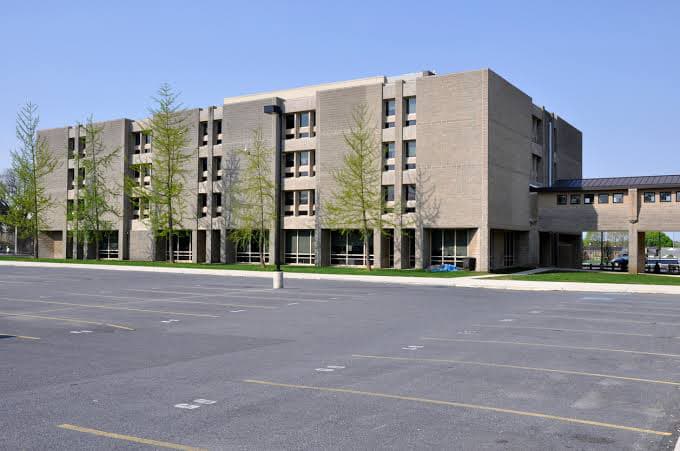
The financial model for converting a 150,000-square-foot office building into a flex-logistics industrial hub breaks down as follows:
- Acquisition Cost: $18,000,000 ($120/sq. ft.)
- Conversion Capital Expenditure (CAPEX): $12,000,000 ($80/sq. ft.)
- Total Project Cost: $30,000,000 ($200/sq. ft.)
- Capital Structure: Senior Construction Loan at $18,000,000 (60% LTC); Private Equity at $12,000,000 (40% LTC).
Conversion scope involves clearing interior partitions, constructing loading docks, retrofitting floor loads to 250–300 lbs per square foot, and expanding ground-floor ceiling clearances.
Prior to conversion, the asset generated a Net Operating Income (NOI) of $900,000 at 50% occupancy. Following repositioning and leasing to third-party logistics (3PL) providers—such as DHL, FedEx, or regional couriers—and e-commerce tenants under Triple Net (NNN) leases, rental rates escalate to $22–$26 per square foot. Upon stabilization, annual NOI reaches $3,100,000. Applying an exit capitalization rate of 6.25% yields a stabilized asset valuation of $49,600,000, generating an Equity Multiple of 2.2x over a 4-year hold period.
Technical Requirements and Retrofitting for Edge Data Centers
Converting office properties into edge data centers (2 to 10 MW capacity) requires a rigorous technical audit of existing MEP (mechanical, electrical, and plumbing) infrastructure. The primary determinant of feasibility is immediate access to high-capacity power utility lines and fiber-optic backbones.
The engineering retrofit must meet the following technical criteria:
- Power Capacity: Delivery of 100 to 150 Watts per square foot of usable floor space. Conversion requires negotiating dedicated medium/high-voltage utility feeder connections with local power providers.
- Structural Floor Loading: Floor slab reinforcement up to 300–400 lbs per square foot to support high-density server racks and Uninterruptible Power Supply (UPS) systems.
- Cooling Systems: Installation of closed-loop chillers and direct-expansion cooling units. Integrating liquid cooling infrastructure reduces Power Usage Effectiveness (PUE) metrics down to 1.15–1.25.
- Redundancy Standards: Dedicated exterior pad space for diesel generator units holding 48–72 hours of continuous fuel supply, conforming to Tier III uptime standards.
CAPEX for edge data center conversions ranges higher, between $250 and $350 per square foot. However, long-term 10-to-15-year lease commitments from enterprise technology firms and cloud providers yield stable cash flows featuring 3–4% annual rent escalations.
Entitlements, Zoning, and Tax Incentives
Executing adaptive reuse strategies requires navigating municipal land use regulations and securing zoning variances. Office assets are typically zoned Commercial Office (CO). Converting to flex-logistics or data center usage requires obtaining a Conditional Use Permit (CUP) or rezoning the parcel to Light Industrial (M-1).
Developers leverage expedited approval pathways by aligning projects with municipal revitalization initiatives aimed at restoring municipal property tax bases.
International private capital typically enters these deals through joint venture structures:
- Joint Venture (JV) Structuring: The international investor acts as a Limited Partner (LP), contributing 80–90% of required equity. A local developer acts as General Partner (GP), committing 10–20% equity while executing daily development management.
- Tax Optimization: Entities are formed as Delaware LLCs or special purpose vehicles (SPVs) taxed as partnerships, eliminating corporate-level double taxation. For non-U.S. investors, distributions are structured to comply with Section 897 of the Internal Revenue Code (FIRPTA) and applicable double taxation treaties.
- Tax Subsidies and Depreciation: Utilizing bonus depreciation mechanisms allows sponsors to accelerate cost recovery on qualifying equipment during Year 1. Properties located in designated Qualified Opportunity Zones allow investors to defer and mitigate capital gains tax obligations when assets are held for more than 10 years.
Deploying private capital into distressed U.S. office conversions offers entry at a low cost basis, creating high-demand infrastructure while capturing yields that significantly outperform conventional real estate asset classes.
This material is for general information only and does not constitute legal, immigration, investment, or tax advice. Program requirements and processing practices may change. Individual results depend on the applicant’s circumstances, visa availability, USCIS decisions, and project performance.