Professional asset selection is built on three distinct levels:
-
Macro Level: State selection based on landlord laws, taxes, and net migration.
-
Meso Level: Analysis of specific markets, submarkets, and neighborhood classes.
-
Micro Level: Underwriting individual properties and inspecting physical condition.
A mistake at the macro level can make an otherwise profitable deal loss-making, even if the house itself was purchased at a steep discount.
Level 1: State and Location Macro-Analysis
US legislation grants individual states broad authority over rental regulation. Markets generally fall into two primary categories.
Landlord-Friendly States Key examples include Texas, Florida, Indiana, Georgia, Ohio, and Alabama.
In these states, the eviction process for non-payment typically takes between 2 and 6 weeks. Statutorily, courts enforce the owner's right to collect rent or regain possession promptly. Rent control restrictions are virtually non-existent, and state corporate and personal income tax burdens remain below the national average.
Tenant-Friendly States Key examples include California, New York, New Jersey, Illinois, and Oregon.
Evicting a non-paying tenant through judicial proceedings in California or New York can stretch from 6 to 12 months. Throughout this period, property owners must cover mortgage payments and property taxes out of pocket. Regulations often cap annual rent increases, and local municipalities strictly govern lease terms and tenant screening.
For consistent cash flow, investors lean toward states experiencing population in-migration and job growth. Investors monitor corporate relocations, infrastructure expansions, and employment trends. When major employers enter a metro area, housing demand rises naturally.
Level 2: Neighborhood Class Analysis
Submarkets within a city are categorized by class, which dictates the balance between immediate Cash Flow and long-term Appreciation.
Class A (Prime Neighborhoods)
-
Properties built within the last 10–15 years, located in top-rated school districts (School Ratings 8–10).
-
Tenant profile: High-earning professionals with strong credit (Credit Scores 720+).
-
Lower immediate yields (Cap Rates 4–5%), but stronger long-term property appreciation potential.
Class B (Stable Middle Class)
-
Properties aged 15–30 years in sound technical condition, located in solid school districts (School Ratings 5–7).
-
Tenant profile: White-collar workers, skilled trades, and mid-level managers (Credit Scores 620–710).
-
Balanced return profile: Cap Rates of 6–8%, stable payment histories, and moderate appreciation.
Class C (Working-Class & Industrial Areas)
-
Older housing stock (40+ years), lower school ratings, and elevated local crime rates.
-
Tenant profile: Blue-collar workforce, hourly workers, or subsidized housing tenants (lower credit histories).
-
High paper yields (Cap Rates 9–12%+). In practice, returns can be eroded by frequent maintenance, lease defaults, tenant turnover, and legal costs.
As an initial filter, investors often reference the 1% Rule. Monthly gross rent should equal at least 1% of the total acquisition cost (purchase price plus immediate renovation). For example, a property acquired for $200,000 should rent for at least $2,000 per month. While the 1% Rule is increasingly rare in high-cost coastal markets like California, it remains a quick screening tool across the Midwest and parts of the Sun Belt.
Level 3: Financial Underwriting
Financial underwriting reveals the true economics of a deal before entering a contract. The core metric is Net Operating Income (NOI).
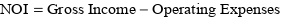
Operating expenses include property taxes, insurance, HOA fees, owner-paid utilities, property management fees, and routine maintenance. Debt service (mortgage principal and interest) is excluded from NOI.
From NOI, two primary valuation metrics are derived:
-
Cap Rate (Capitalization Rate):
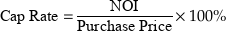
Measures an asset's unleveraged yield, assuming an all-cash purchase.
-
Cash-on-Cash Return:
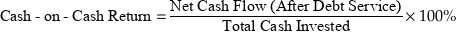
Measures the annual cash return on actual equity invested (down payment, closing costs, and upfront repairs) after deducting monthly mortgage payments.
Factoring in recurring operating expenses prevents negative cash flow. A sound financial model must account for four major line items:
-
Property Tax: Varies by county, typically ranging from 0.6% to 2.5% of assessed value annually.
-
Insurance: Homeowners and hazard insurance policies (factoring in flood or hurricane riders where applicable).
-
Vacancy Rate: An allowance for tenant turnover and downtime (typically budgeted at 5–8% of gross annual rent).
-
Capital Expenditures (CapEx): Reserves set aside for big-ticket replacements, such as roofs, HVAC systems, or water heaters (typically 5–10% of gross rent).
Neighborhood Class Comparison
|
Neighborhood Class |
Return Strategy |
Risk Profile |
Tenant Profile |
Target Cap Rate |
|---|---|---|---|---|
|
Class A |
Appreciation Focus |
Low |
Engineers, Executives, Physicians |
4% – 5.5% |
|
Class B |
Balanced (Cash Flow + Growth) |
Moderate |
Office Staff, Teachers, Managers |
6% – 8% |
|
Class C |
Cash Flow Focus |
High |
Hourly Workers, Unskilled Trades |
8.5% – 12% |
Physical Due Diligence Checklist
Once preliminary numbers clear underwriting targets, physical due diligence begins. Hiring a licensed Property Inspector is a critical milestone. The process yields a comprehensive Property Inspection Report (typically 30–50 pages) detailing structural integrity and mechanical systems.
Key structural components to evaluate include:
-
Roof: Asphalt shingle roofs generally carry a 15–20 year lifespan. Complete roof replacements typically range between $8,000 and $15,000.
-
Foundation: Major settling or foundation cracks require structural engineering remediation, which can exceed $20,000.
-
HVAC Systems: Heating and cooling units average a 10–15 year lifespan. Full system replacements cost roughly $5,000 to $9,000.
-
Electrical & Plumbing: Outdated aluminum wiring or polybutylene piping often necessitates complete system rewiring or re-piping to remain insurable.
Inspection findings provide objective leverage during contract negotiations. Investors can request a Price Reduction or Seller Credits at closing to cover identified repair costs.
Concurrently, a Title Company conducts a title search to ensure clean ownership transfer. They verify that the property is free of outstanding liens, back taxes, municipal utility debts, or mechanic's liens from prior contractors. Obtaining Title Insurance protects the buyer against undisclosed ownership claims or encumbrances.
A systematic approach to property selection limits unexpected capital expenditures and builds a stable rental business in the US.
This material is for general information only and does not constitute legal, immigration, investment, or tax advice. Program requirements and processing practices may change. Individual results depend on the applicant’s circumstances, visa availability, USCIS decisions, and project performance.