Market Dynamics and Financial Metrics of Commercial Assets
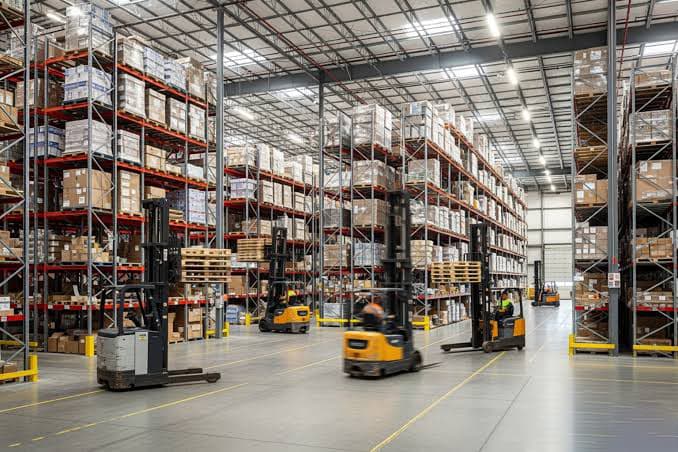
The industrial logistics sector maintains an overall vacancy rate of 5.4% to 5.8% across key distribution hubs: the Inland Empire (California), Dallas–Fort Worth (Texas), Indianapolis, and the Port of New Jersey. Primary tenants include 3PL logistics operators, national retailers, and e-commerce companies (Amazon, Walmart, FedEx).
Average lease rates for Class A warehouse space range from $9.50 to $14.00 per square foot per year (NNN). Lease agreements are typically structured for 5-to-10-year terms with annual escalation clauses of 3% to 4%.
In retail real estate, demand shows a structural tilt toward Grocery-Anchored Centers and Single-Tenant Net Lease (STNL) assets. Vacancy rates in these segments remain tight at 4.6% to 5.1%. Supermarket chains (Trader Joe’s, Kroger, Publix) and pharmacy retailers (CVS, Walgreens) drive stable foot traffic. Lease rates vary from $18 to $35 per square foot NNN.
Operational expense structures in both sectors are governed by Triple Net (NNN) leases. The tenant assumes three core categories of operating costs:
-
Property Tax: 1.2% to 2.8% of assessed value per year.
-
Property Insurance: $0.35 to $0.75 per square foot.
-
Common Area Maintenance (CAM): $1.20 to $3.50 per square foot.
This setup allows the investor to receive a Net Operating Income (NOI) shielded from most property-level operational cost fluctuations.
Legal Structuring and Tax Norms for Foreign Investors
Foreign investors structure transactions through two-tier corporate entities to optimize tax obligations and shield underlying assets. Direct personal ownership is avoided due to U.S. estate tax exposure, which reaches rates up to 40% on U.S.-sited assets exceeding $60,000.
The standard corporate structure includes:
-
State-Level LLC (Limited Liability Company): Formed in the state where the property resides (Texas, Delaware, Florida). The LLC holds direct title to the real estate.
-
C-Corporation or Blocker Corporation: Incorporated in Delaware or Wyoming. It holds a 100% equity stake in the LLC and functions as a tax blocker.
Tax rates and mechanics for foreign investment structures:
-
Corporate Income Tax: The federal rate is 21%. Additional state corporate tax ranges from 0% (Texas, Florida, Wyoming) to 11.5% (New Jersey).
-
Depreciation: Under IRC Section 168, commercial buildings (excluding land value) are depreciated over a 39-year schedule. Cost Segregation studies allow investors to accelerate depreciation on specific property components (lighting, pavement, mechanical systems), writing off 20% to 30% of the building's cost basis within the first 5 years.
-
Foreign Investment in Real Property Tax Act (FIRPTA): Upon disposition, the buyer must withhold 15% of the gross sale price to satisfy potential capital gains tax liabilities of the foreign seller.
-
Section 1031 Exchange: Allows investors to defer capital gains taxes by reinvesting all net sale proceeds into a like-kind commercial property within 180 days.
Financing Models and Debt Capital Structures
Acquisitions of commercial assets rely on senior debt from commercial banks or agency lenders (Fannie Mae, Freddie Mac).
Standard underwriting parameters for U.S. commercial real estate:
-
Loan-to-Value (LTV): Lenders provide 60% to 70% of appraised property value.
-
Debt Service Coverage Ratio (DSCR): Minimum required coverage sits at 1.25x to 1.35x, requiring NOI to maintain this cushion over annual debt service obligations.
-
Interest Rates: Fixed and floating commercial mortgage rates range from 6.2% to 7.5% per annum on 5-to-10-year loan terms with 25-to-30-year amortization schedules.
|
Project Metric |
Grocery-Anchored Retail Center |
Class A Logistics Center |
|---|---|---|
|
Asset Purchase Price |
$12,000,000 |
$25,000,000 |
|
Debt Senior Financing (65% LTV) |
$7,800,000 |
$16,250,000 |
|
Equity Contribution |
$4,200,000 |
$8,750,000 |
|
Net Operating Income (NOI) |
$780,000 (6.5% Cap Rate) |
$1,375,000 (5.5% Cap Rate) |
|
Annual Debt Service (1.30x DSCR) |
$550,000 |
$1,020,000 |
|
Net Pre-Tax Cash Flow |
$230,000 |
$355,000 |
|
Cash-on-Cash Return (CoC) |
5.47% (pre-depreciation) |
4.05% (pre-depreciation) |
|
Target Project IRR (including appreciation) |
11.5–13.0% |
12.0–14.2% |
Securing debt financing requires foreign investors to present audited financial statements, proof of capital origin, and an experienced domestic operating partner (Sponsor/General Partner) managing the U.S. asset.
Step-by-Step Acquisition Process and Due Diligence
Acquiring U.S. commercial real estate takes between 90 and 150 days and follows a strict legal and financial timeline:
-
Structuring and Selection (30 days): Entity registration, establishing U.S. banking accounts (Chase, Bank of America, Wells Fargo), and executing a Letter of Intent (LOI) with the seller.
-
Property Due Diligence (45–60 days):
-
Phase I Environmental Site Assessment (ESA): Environmental review of soil and groundwater for contaminants. Detection of issues triggers a Phase II investigation.
-
Property Condition Assessment (PCA): Structural engineering inspection of mechanical systems, roofing, foundation, and parking areas.
-
Lease Audit: Verification of tenant lease contracts, security deposits, and execution of Estoppel Certificates confirming no landlord defaults.
-
Title Search & Title Insurance: Verification of unencumbered property title and issuance of lender/owner title insurance policies.
-
Underwriting and Loan Finalization (30–45 days): Securing final approval from the bank's credit committee and completing an independent Appraisal Report.
-
Closing (1–3 days): Execution of the Purchase and Sale Agreement (PSA), funding the escrow account managed by the Escrow Agent, and recording the deed at the County Recorder's office.
Asset management is delegated to a licensed third-party Property Management Company. Management fees average 3% to 5% of gross collected rent for retail centers and 2% to 3% for industrial logistics assets.
This material is for general information only and does not constitute legal, immigration, investment, or tax advice. Program requirements and processing practices may change. Individual results depend on the applicant’s circumstances, visa availability, USCIS decisions, and project performance.